 payeh payeh
2 hours ago in Business Services
High Authority Social Bookmarking Site for Indian SEO in 2026 - A2Bookmarks India
A2Bookmarks India stands as the nation's premier social bookmarking site, expertly crafted for Indian users and businesses to enhance their digital visibility. Our social bookmarking site for India allows you to seamlessly save, organize, and promote essential web content while engaging with India's rapidly expanding online community. As one of the most effective Indian social bookmarking sites for 2026, our advanced SEO-optimized features help significantly boost website traffic and strengthen search engine presence across diverse markets. Join our thriving network among India's top social bookmarking sites to discover curated content, connect with industry professionals, and accelerate your digital growth. Start maximizing your online impact today with our tailored platform among the best social bookmarking sites for the Indian market designed specifically for the Indian digital landscape.
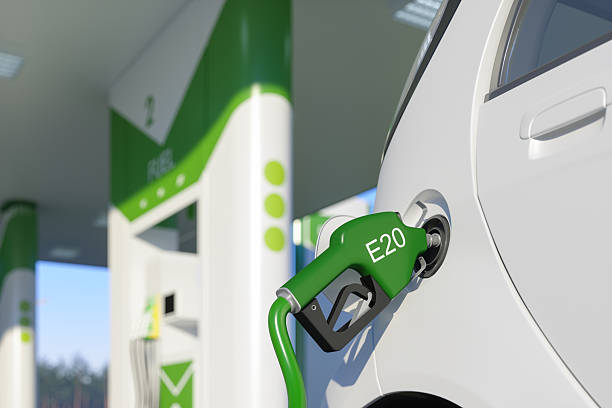
E-Fuels Market Outlook: Key Trends Shaping 2026–2032 marknteladvisors.com
payeh payeh
2 hours ago in Business Services
Low-carbon fuels are gaining attention as governments, energy companies, and transport operators seek alternatives for applications where direct electrification remains difficult. Aviation and maritime transport are particularly relevant because their energy-density requirements make a rapid transition to battery-based systems more challenging. This is creating interest in synthetic fuels produced using renewable electricity, hydrogen, and captured carbon.
The E-Fuels Market covers synthetic fuels produced by combining renewable hydrogen with carbon-based feedstocks or other chemical pathways to create fuel products compatible with established energy systems. According to the e-fuel market study published by Markntel Advisor, the global industry is projected to expand from USD 10.29 billion in 2026 to USD 32.29 billion by 2032, representing a 21% CAGR during 2026–2032. The study identifies aviation, marine applications, renewable hydrogen infrastructure, and Power-to-X development as important areas shaping the market outlook.
The transition is increasingly linked to the development of supporting infrastructure rather than fuel production alone. Renewable electricity generation, electrolyzer capacity, green hydrogen availability, carbon capture, fuel synthesis facilities, transportation infrastructure, and long-term offtake agreements all influence the ability of projects to move from demonstration to commercial operation. As these interconnected elements develop, the economics and scalability of synthetic fuel production are becoming increasingly important industry considerations.
Aviation and Maritime Demand Strengthen Adoption
Aviation represents a particularly significant application because aircraft require energy-dense liquid fuels and cannot readily transition to conventional battery-electric propulsion for most long-haul operations. The International Energy Agency notes that aviation and marine transport remain more reliant on fuel-based decarbonization solutions than road transport, where electrification has greater potential. This creates a role for hydrogen-based synthetic fuels alongside other sustainable fuel pathways. IEA analysis of e-fuels highlights their potential contribution to the decarbonization of these harder-to-electrify sectors.
Policy frameworks are also creating clearer demand signals. The European Union’s ReFuelEU Aviation framework requires sustainable aviation fuel use to increase over time, including a dedicated requirement for synthetic aviation fuels. Synthetic aviation fuels are required to reach 1.2% of fuel supplied at EU airports by 2030 and 35% by 2050. These targets provide a regulatory basis for project development while encouraging fuel suppliers and aviation stakeholders to consider future synthetic-fuel availability. European Commission information on ReFuelEU Aviation outlines these requirements.
Power-to-Liquid Gains Strategic Importance
Power-to-Liquid (PtL) is emerging as an important production route because it can convert renewable electricity, hydrogen, and carbon into liquid fuels that are compatible with applications such as aviation and shipping. The Markntel Advisor study indicates that PtL represented approximately 46% of the global market in 2026. Its relevance is supported by the possibility of producing liquid hydrocarbons that can fit into existing fuel logistics, although commercial viability remains dependent on electricity costs, electrolyzer performance, carbon availability, and overall plant efficiency.
The development of modular and containerized PtL systems is another notable industry trend. Modular production can allow capacity to be added incrementally rather than requiring every project to begin with a very large centralized facility. This approach may also support deployment closer to renewable power sources, carbon feedstocks, ports, or industrial consumers. Projects involving modular synthesis units therefore illustrate how technology configuration is evolving alongside the broader effort to commercialize synthetic fuel production.
Cost and Infrastructure Remain Key Constraints
Despite the growth outlook, production economics remain a major challenge. Synthetic fuels require multiple energy-intensive stages, including renewable electricity generation, hydrogen production, carbon processing, and fuel synthesis. Each stage can influence the final cost of the fuel. The availability of affordable renewable electricity and efficient electrolyzers is therefore critical, while access to suitable carbon sources and supporting infrastructure can determine whether individual projects achieve commercial scale.
Financing and offtake agreements are equally important because large production facilities require significant upfront investment before revenue generation begins. Long-term purchasing commitments from airlines, shipping companies, industrial users, or fuel distributors can improve visibility for project developers. Regulatory incentives and carbon-intensity requirements can also affect project economics by narrowing the cost difference between synthetic fuels and conventional alternatives.
Europe Maintains a Leading Position
Europe currently represents the largest regional market, accounting for approximately 45% of the global market in 2026, according to the Markntel Advisor study. The region’s position reflects a combination of fuel-decarbonization policies, synthetic aviation-fuel requirements, renewable energy development, and expanding hydrogen infrastructure. Germany, France, the Netherlands, Spain, and other European markets are also associated with projects aimed at increasing synthetic fuel production capacity.
Other regions are developing their own pathways. North America is supported by clean-fuel policies and investment incentives, while countries in Asia-Pacific are examining synthetic fuels as part of broader energy-security and decarbonization strategies. India, for example, is expanding its green hydrogen ecosystem, which could support future feedstock availability for synthetic fuel production. These regional developments suggest that production and consumption may increasingly be distributed across locations with access to renewable electricity, hydrogen, carbon resources, and export infrastructure.
What Could Shape the Industry Through 2032?
The next phase of development is likely to depend on whether announced projects progress into construction and commercial operations. Technology improvements can help reduce production complexity, while larger electrolyzer deployments and expanding renewable generation could improve input economics over time. At the same time, consistent regulations and credible demand commitments will remain important for reducing investment uncertainty.
Overall, the outlook reflects an industry moving from pilot-scale experimentation toward early commercialization. Aviation and maritime applications are likely to remain central because they have fewer immediate electrification options, while Power-to-Liquid technology can provide a pathway for producing liquid fuels compatible with established infrastructure. The pace of expansion through 2032 will ultimately depend on the interaction between production costs, renewable energy availability, policy support, project financing, and the successful commissioning of new capacity.
voters
Report Story 
Related Stories

Recent Stories